Blog
The 100% Payout Trap: What Advisors Should Calculate Before Going Independent
By Eric Grinberg
29 Sep 2026
An attractive payout percentage doesn’t always translate to a more profitable business. Here’s what advisors should consider before making the move.
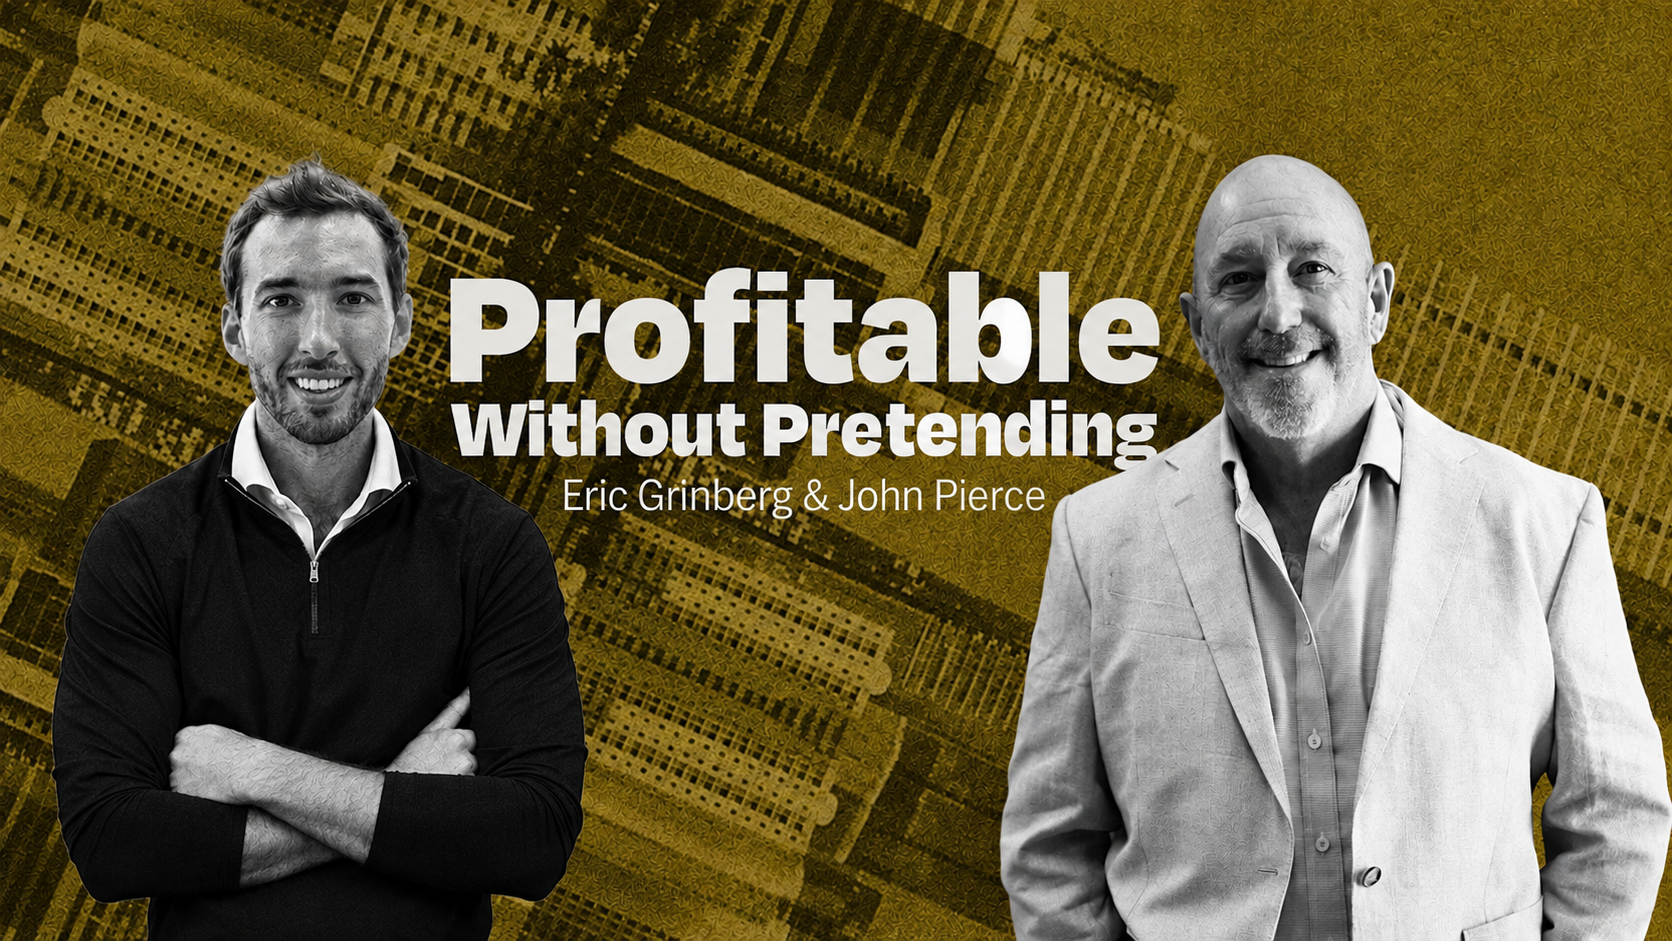
From the Profitable Without Pretending Podcast
Hosted by Revolt CEO Eric Grinberg, Profitable Without Pretending features candid conversations with industry leaders about the opportunities, challenges, and financial realities of advisor independence.
This article draws on a conversation with John Pierce, a longtime financial services executive.
A 100% payout sounds pretty good on paper. After years of sharing revenue with a firm, the opportunity to keep everything you generate can be a compelling reason to go independent. But before getting too excited about that number, there’s an important question to ask: How much of that revenue will actually make it into your pocket?
The economics of independence are more complicated than a percentage on a payout grid. Between operating costs, platform fees, and other ongoing expenses, a higher payout doesn’t necessarily mean a more profitable business. Understanding what you’ll actually take home requires looking beyond the headline number.
A 100% payout doesn’t mean you keep 100%
Going independent means taking on expenses that may have previously been covered by an employer, including staffing, technology, compliance, supervision, office space, and other operational needs. Even when a firm advertises a 100% payout, someone still has to pay the bills.
For advisors used to having operational support built into their existing firm, the costs of replacing those services can be easy to underestimate, especially since independent models vary in what they provide and how they charge for it. Two firms might advertise similar payouts, but differences in general and administrative (G&A) charges, platform fees, and other operating expenses can have a meaningful impact on what advisors ultimately take home.
To get a clearer picture of the economics, advisors should be asking:
- What platform, technology, and administrative fees will I pay?
- Which services are included, and which come at an additional cost?
- What will staffing, compliance, and supervision cost?
- How will expenses change as my business grows?
- After everything is accounted for, how much cash flow will the business actually generate?
The answers may reveal that a model offering a lower payout but more comprehensive support makes better financial sense than one advertising a higher payout with substantial additional expenses. What matters is understanding the total cost of doing business and how each arrangement affects profitability.
Don’t let the upfront check distract from the long-term math
Payout percentages aren’t the only numbers that can make a transition look attractive. Upfront offers can also be compelling, particularly for established advisors and larger teams, but the initial payment is only one part of the financial equation.
To understand whether a move makes sense, advisors need to evaluate the economics over the full term of the agreement, including expected revenue, ongoing expenses, and the cash flow the business can realistically generate. A deal that looks appealing on day one may be less attractive if operating costs consistently eat into earnings.
Beyond evaluating the initial deal, advisors also need to consider how their operating costs might change as the business grows. John Pierce, a longtime financial services executive, shared his experience seeing organizations expand their staffing and infrastructure before revenue could support the added costs. In some cases, he observed, businesses with substantial production ended up with surprisingly little profit.
His advice for larger advisory businesses is to grow carefully rather than hiring too far ahead of demand. Additional staff and infrastructure can support expansion, but they also create ongoing obligations that need to be factored into the business’s financial plans.
Those decisions can also have implications beyond day-to-day profitability. For advisors considering an eventual sale or succession plan, Pierce also highlights EBITDA (earnings before interest, taxes, depreciation, and amortization) as a measure worth considering when evaluating a business. Managing expenses carefully today can help advisors build a more profitable business with greater long-term value.
The bottom line
Independence offers advisors the opportunity to gain greater control over how they operate and serve clients. But with that control comes greater responsibility for the financial health of the business, making it important to evaluate what an attractive payout will mean in practice.
Before making a move, advisors should understand what they’ll earn, what they’ll spend, and how much cash flow they can realistically expect. Just as importantly, they should consider whether the affiliation model supports the business they want to build over time.
The best deal isn’t necessarily the one with the highest payout. It’s the one that leaves you with a stronger business.
Want to dig deeper?
Eric Grinberg and John Pierce explore the economics of independence, business valuations, and more in an episode of Profitable Without Pretending. Watch the full conversation here.
About the author